

Analysis: Can the PM steer UK through choppy global waters?
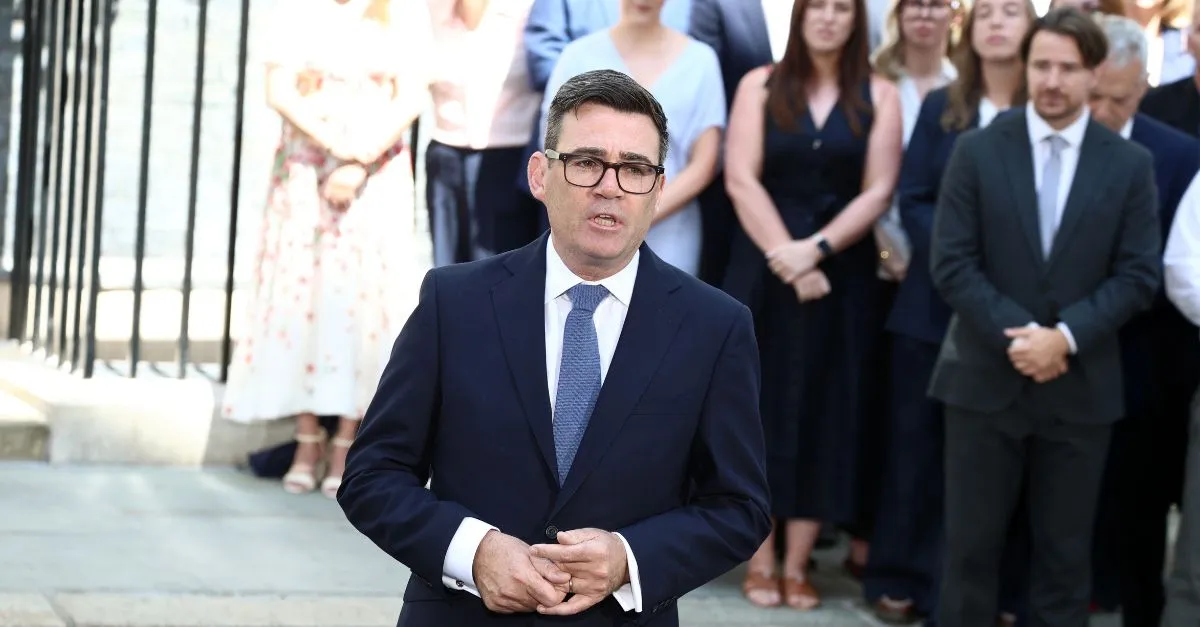

Andy Burnham faces a host of economic pressures, reports Ian Taylor
The end of peak summer and of the ‘silly season’ for news may hit harder than normal next week when MPs return to Parliament.
The government of Andy Burnham, in post for barely the duration of the school holidays, must face up to the challenges which led to him becoming prime minister, when in June he was not even an MP.
Burnham has gained a degree of popularity with a down-to-earth approach and focus on bus fares, small businesses, the cost of living and homelessness. But the real business of government starts now.
Central bankers were due in Jackson Hole, Wyoming, this week for an annual three-day ‘economic symposium’ organised by the US Federal Reserve, whose chair Kevin Warsh will be in the spotlight.
Warsh’s reluctance to issue guidance on whether interest rates are likely to move up or down is credited with diminishing confidence in the Fed – the ultimate backstop of the global financial system.
Deloitte UK chief economist Debapratim De noted the Jackson Hole event “comes at a time of turbulence in US treasury markets”.
Indeed, it does. US treasury secretary Scott Bessent has been trying and failing to shore up the US bond market by pledging the Treasury will double its purchase of long-term bonds in what the Financial Times described as a “running battle [that] is starting to look like his boss’s war in Iran”.
US borrowing costs are now at “extraordinary heights”, the FT noted, and “other countries will end up paying more to borrow too”.
Unfortunately, the UK is in the lead among these, with an additional £1.8 billion unexpectedly added to the deficit in July and an inflation rate of 2.9% last month.
The escalating US-Canadian trade war only adds to the sense of chaos, with Canadian PM Mark Carney declaring at the weekend: “You’re at war when you’re attacked, and we got attacked.”
In the circumstances, chancellor John Healey’s Budget, due on October 28, appears likely to be “as much a non-event as possible”, according to one analyst, with the headroom between tax income and spending eroding.
Bessent has not just roiled the markets with his intervention on bonds. On Monday he declared an “economic D-Day” against Iran, threatening any government assisting or trading with Tehran.
Only last week, Trump threatened to bomb Oman – a tourism jewel in the region – in fury at the prospect of a deal on opening the Strait of Hormuz on joint Iran-Oman terms which would include a charge on ships transiting the strait.
So, we dare not see Bessent’s economic threats – which were immediately dismissed as ineffective by analysts – as reducing the risk of renewed war.
The threat of war was also highlighted at the weekend by the US ambassador to Turkey suggesting an Israeli attack on an air base in Syria last week was an attempt to “bait” Turkey into conflict.
Israel admitted it targeted the base due to fears Turkey would establish itself at the site 43 miles from the Turkish border.
The threats to travel are all too obvious. There could be much riding on Foreign Office travel advice as we move into autumn.
More Content




More Content


Jacobs Media is a company registered in England and Wales, company number 08713328. 3rd Floor, 52 Grosvenor Gardens, London SW1W 0AU
© 2025 Jacobs Media